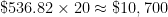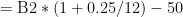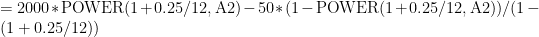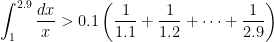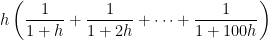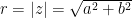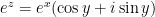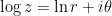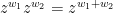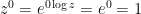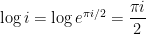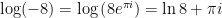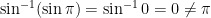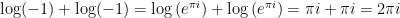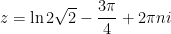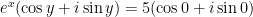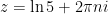Exponential growth and decay (Part 9): Amortization tables

This post is inspired by one of the questions that I pose to our future high school math teachers during our Friday question-and-answer sessions. In these sessions, I play the role of a middle- or high-school student who’s asking a tricky question to his math teacher. Here’s the question:

A student asks, “My father bought a house for $200,000 at 12% interest. He told me that by the time he fi nishes paying for the house, it will have cost him more than $500,000. How is that possible? 12% of $200,000 is only $24,000.”

Without fail, these future teachers don’t have a good response to this question. Indeed, my experience is that most young adults (including college students) have never used an amortization table, which is the subject of today’s post.

In the past few posts, we have considered the solution of the following recurrence relation, which is often used to model the payment of a mortgage or of credit-card debt:
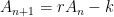
A_{n+1} = r A_n - k

With this difference equation, the rate at which the principal is reduced can be simply computed using Microsoft Excel. This tool is called an amortization schedule or an amortization table; see E-How for the instructions of how to build one. Here’s a sample Excel spreadsheet that I’ll be illustrating below: Amortization schedule. My personal experience is that many math majors have never seen such a spreadsheet, even though they are familiar with compound interest problems and certainly have the mathematical tools to understand this spreadsheet.

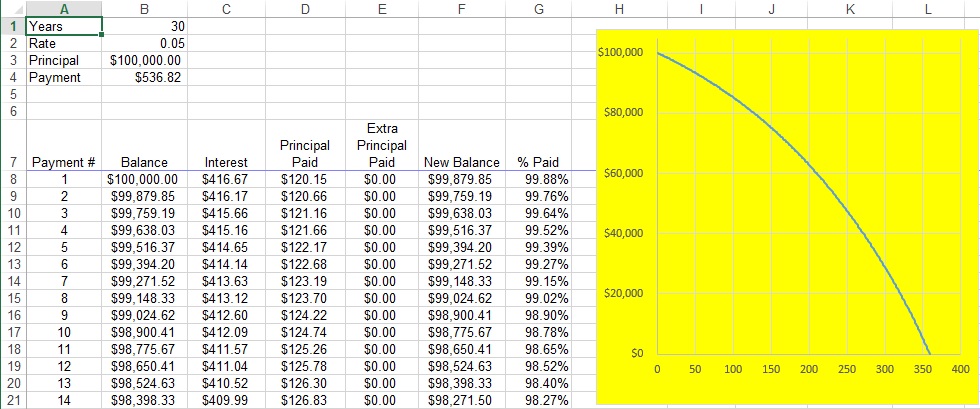
Here’s a screen capture from the spreadsheet:
Amortization1

The terms of the loan are typed into Cells B1 (length of loan, in years), B2 (annual percentage rate), and B3 (initial principal). Cell B4 is computed from this information using the Microsoft Excel command \hbox{PMT}:

=\hbox{PMT}(\hbox{B2}/12,\hbox{B1}*12,-\hbox{B3})

This is the amount that must be paid every month in order to pay off the loan in the prescribed number of years. Of course, there is a formula for this:

M = \displaystyle \frac{Pr}{12 \displaystyle \left[1 - \left( 1 + \frac{r}{12} \right)^{-12t} \right]}

I won’t go into the derivation of this formula here, as it’s a bit complicated. Notice that this formula does not include escrow, points, closing costs, etc. This is strictly the amount of money that’s needed to pay down the principal.

The table, beginning in Row 8 of the above picture, shows how quickly the principal will be paid off. In row 8, the interest that’s paid for that month is  computed by
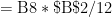
=\hbox{B8} * \$ \hbox{B}\$\hbox{2}/12

Therefore, the amount of the monthly payment that actually goes toward paying down the principal will be

= \$\hbox{B}\$\hbox{4} - \hbox{C8}

Column E provides an opportunity to pay something extra each month; more on this later. So, after taking into account the payments in columns D and E, the amount remaining on the loan is recorded in Cell F8:
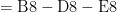
= \hbox{B8} - \hbox{D8} - \hbox{E8}

This amount is then copied into Cell B9, and then the pattern can be filled down.

The yellow graph shows how quickly the balance of the loan is paid off over the length of the loan. A picture is worth a thousand words: in the initial years of the loan, most of the payments are gobbled up by the interest, and so the principal is paid off slowly. Only in the latter years of the loan is the principal paid off quickly.

So, it stands to reason that any extra payments in the initial months and years of the loan can do wonders for paying off the loan quickly. For example, here’s a screenshot of what happens if an extra $200/month is paid only in the first 12 months of the loan:
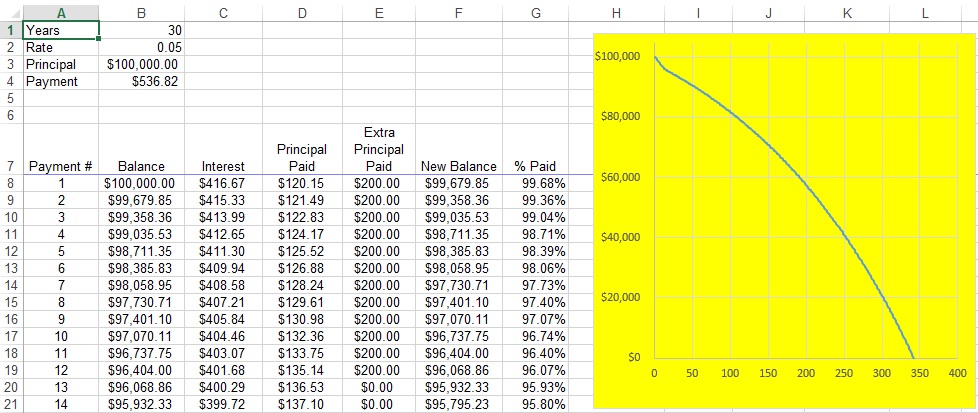
AmortizationwA definite bend in the graph is evident in the initial 12 months until the normal payment is resumed in month 13. As a result of those extra payments, the curve now intersects the horizontal axis around 340. In other words, 20 fewer months are required to pay off the loan. Stated another way, the extra payments in the first year cost an extra \$200 \times 12 = \$2400. However, in the long run, those payments saved about \$536.82 \times 20 \approx \$10,700!
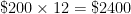
Exponential growth and decay (Part 8): Paying off credit-card debt via recurrence relations

The following problem in differential equations has a very practical application for anyone who has either (1) taken out a loan to buy a house or a car or (2) is trying to pay off credit card debt. To my surprise, most math majors haven’t thought through the obvious applications of exponential functions as a means of engaging their future students, even though it is directly pertinent to their lives (both the students’ and the teachers’).

You have a balance of $2,000 on your credit card. Interest is compounded continuously with a rate of growth of 25% per year. If you pay the minimum amount of $50 per month (or $600 per year), how long will it take for the balance to be paid?

In previous posts, I approached this problem using differential equations. There’s another way to approach this problem that avoids using calculus that, hypothetically, is within the grasp of talented Precalculus students. Instead of treating this problem as a differential equation, we instead treat it as a first-order difference equation (also called a recurrence relation):

A_{n+1} = r A_n - k

The idea is that the amount owed is multiplied by a factor r (which is greater than 1), and from this product the amount paid is deducted. With this approach — and unlike the approach using calculus — the payment period would be each month and not per year. Therefore, we can write
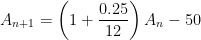
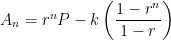
A_{n+1} = \displaystyle \left( 1 + \frac{0.25}{12} \right) A_n - 50

Notice that the meaning of the 25% has changed somewhat… it’s no longer the relative rate of growth, as the 25% has been equally divided for the 12 months. The solution of this difference equation is

A_n = r^n P - k \left( \displaystyle \frac{1 - r^n}{1-r} \right)

green line

A great advantage of using a difference equation to solve this problem is that the solution can be easily checked with a simple spreadsheet. (Indeed, pedagogically, I would recommend showing a spreadsheet like this before doing any of the calculations of the previous few posts, so that students can begin to wrap their heads around the notion of a difference equation before the solution is presented.)

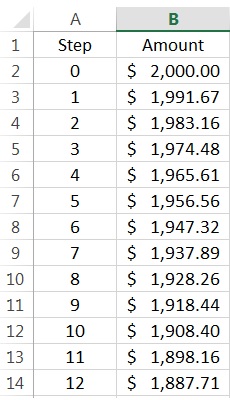
To start the spreadsheet, I wrote “Step” in Cell A1 and “Amount” in Cell B1. Then I entered the initial conditions: 0 in Cell A2 and 2000 in Cell B2. (In the screenshot below, I changed the format of column B to show dollars and cents.) Next, I entered =\hbox{A2}+1 in Cell A3 and

=\hbox{B2}*(1+0.25/12)-50

in Cell B3. Finally, I copied the pattern in Cells A3 and B3 downward. Here’s the result:

creditcardexcel1After the formula the algebraic solution of the difference equation has been found, this can be added to the spreadsheet in a different column. For example, I added the header “Predicted Amount” in Cell D1. In Cell D2, I typed the formula

=2000*\hbox{POWER}(1+0.25/12,\hbox{A2})-50*(1-\hbox{POWER}(1+0.25/12,\hbox{A2}))/(1-(1+0.25/12))

Finally, I copied this pattern down the Column D. Here’s the result:

creditcardexcel2Invariably, when I perform a demonstration like this in class, I elicit a reaction of “Whoa…. it actually works!” Even for a class of math majors. Naturally, I tease them about this… they didn’t believe me when I used algebra, but now it has to be true because the computer says so.

Here’s the spreadsheet that I used to make the above pictures: CreditCardDebt.


Different definitions of e (Part 12): Numerical computation

In this series of posts, we have seen that the number e can be thought about in three different ways.

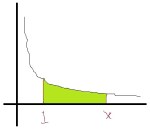
1. e defines a region of area 1 under the hyperbola y = 1/x.logarea2. We have the limits

e = \displaystyle \lim_{h \to 0} (1+h)^{1/h} = \displaystyle \lim_{n \to \infty} \left(1 + \frac{1}{n} \right)^n.

These limits form the logical basis for the continuous compound interest formula.

3. We have also shown that \frac{d}{dx} \left(e^x \right) = e^x. From this derivative, the Taylor series expansion for e^x about x = 0 can be computed:

e^x = \displaystyle \sum_{n=0}^\infty \frac{x^n}{n!}

Therefore, we can let x = 1 to find e:

e = \displaystyle \sum_{n=0}^\infty \frac{1}{n!} = \displaystyle 1 + 1 + \frac{1}{2} + \frac{1}{6} + \frac{1}{24} + \dots

green line

In yesterday’s post, I showed that using the original definition (in terms of an area under a hyperbola) does not lend itself well to numerically approximating e. Let’s now look at the other two methods.

2. The limit e = \displaystyle \lim_{n \to \infty} \left(1 + \frac{1}{n} \right)^n gives a somewhat more tractable way of approximating e, at least with a modern calculator. However, you can probably imagine the fun of trying to use this formula without a calculator.
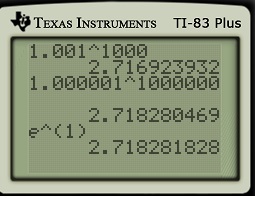
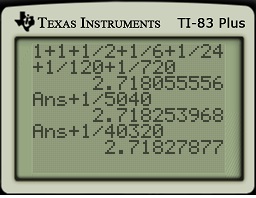
ecalculator3. The best way to compute e (or, in general, e^x) is with Taylor series. The fractions \frac{1}{n!} get very small very quickly, leading to rapid convergence. Indeed, with only terms up to 1/6!, this approximation beats the above approximation with n = 1000. Adding just two extra terms comes close to matching the accuracy of the above limit when n = 1,000,000.
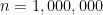
ecalculator2

More about approximating e^x via Taylor series can be found in my previous post.


Different definitions of e (Part 11): Numerical computation

In this series of posts, we have seen that the number e can be thought about in three different ways.

1. e defines a region of area 1 under the hyperbola y = 1/x.logarea2. We have the limits

e = \displaystyle \lim_{h \to 0} (1+h)^{1/h} = \displaystyle \lim_{n \to \infty} \left(1 + \frac{1}{n} \right)^n.

These limits form the logical basis for the continuous compound interest formula.

3. We have also shown that \frac{d}{dx} \left(e^x \right) = e^x. From this derivative, the Taylor series expansion for e^x about x = 0 can be computed:

e^x = \displaystyle \sum_{n=0}^\infty \frac{x^n}{n!}

Therefore, we can let x = 1 to find e:

e = \displaystyle \sum_{n=0}^\infty \frac{1}{n!} = \displaystyle 1 + 1 + \frac{1}{2} + \frac{1}{6} + \frac{1}{24} + \dots

green line

Let’s now consider how the decimal expansion of e might be obtained from these three different methods.

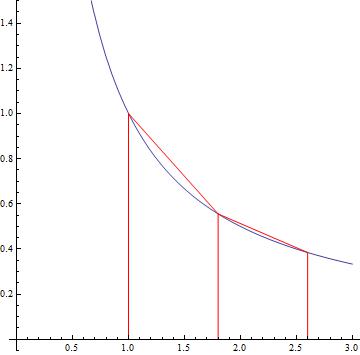
1. Finding e using only the original definition is a genuine pain in the neck. The only way to approximate e is by trapping the value of e using various approximation. For example, consider the picture below, showing the curve y = 1/x and trapezoidal approximations on the intervals [1,1.8] and [1.8,2.6]. (Because I need a good picture, I used Mathematica and not Microsoft Paint.)
approx_e_lower

Each trapezoid has a (horizontal) height of h = 0.8. Furthermore, the bases of the first trapezoids have length \displaystyle \frac{1}{1} = 1 and \displaystyle \frac{1}{1.8}, while the bases of the second trapezoid of length \displaystyle \frac{1}{1.8} and \displaystyle \frac{1}{2.6}. Notice that the trapezoids extend above the hyperbola, so that
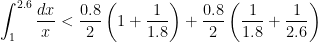
\displaystyle \int_1^{2.6} \frac{dx}{x} < \displaystyle \frac{0.8}{2} \left( 1 + \frac{1}{1.8} \right) + \frac{0.8}{2} \left( \frac{1}{1.8} + \frac{1}{2.6} \right)

\displaystyle \int_1^{2.6} \frac{dx}{x} < 0.9983 < 1

However, the number e is defined to be the place where the area under the curve is exactly equal to 1, and so

\displaystyle \int_1^{2.6} \frac{dx}{x} < \displaystyle \int_1^{e} \frac{dx}{x}

In other words, we know that the area between 1 and 2.6 is strictly less than 1, and therefore a number larger than 2.6 must be needed to obtain an area equal to 1.

Great, so e > 2.6. Can we do better? Sadly, with two equal-sized trapezoids, we can’t do much better. If the height of the trapezoids was h and not 0.8, then the sum of the areas of the two trapezoids would be

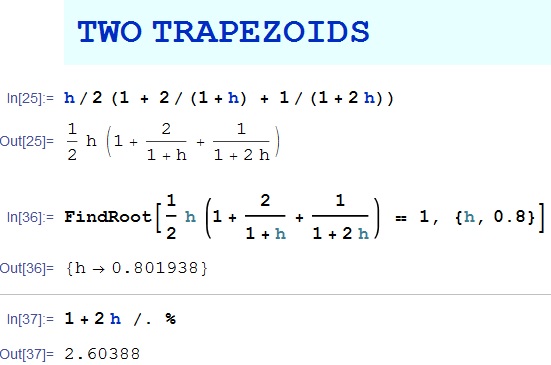
\displaystyle \frac{h}{2} \left( 1 + \frac{2}{1+h} + \frac{1}{1+2h} \right)

By either guessing and checking — or with the help of Mathematica — it can be determined that this function of h is equal to 1 at approximately h \approx 0.8019, thus establishing that e > 1 + 2h \approx 2.6039.

e_twotrapezoids

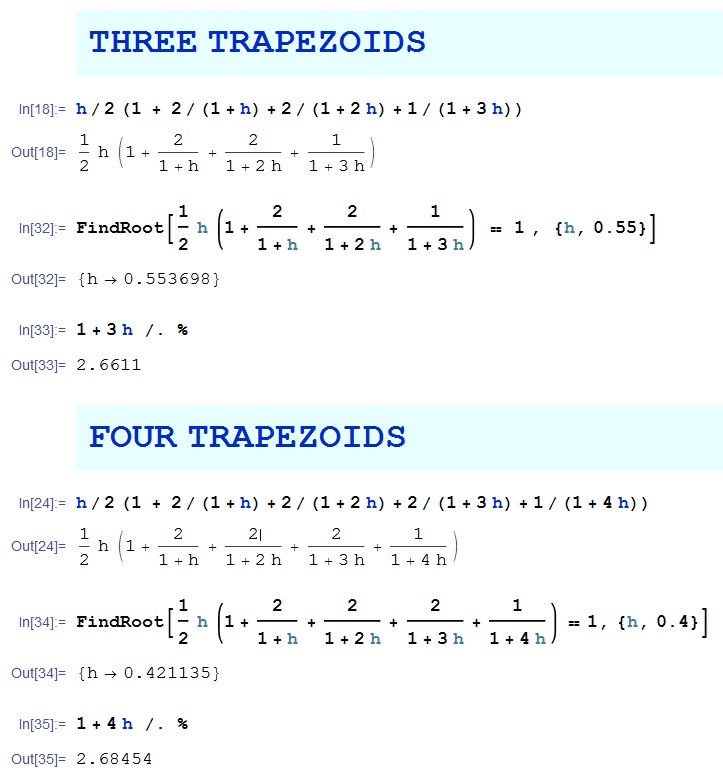
We can try to better with additional trapezoids. With four trapezoids, we can establish that e > 2.6845.

e_fourtrapezoids

With 100 trapezoids, we can show that e > 2.71822.

e_hundredtrapezoidsHowever, trapezoids can only provide a lower bound on e because the original trapezoids all extend over the hyperbola.

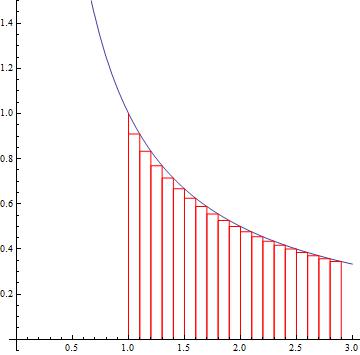
green lineTo obtain an upper bound on e, we will use a lower Riemann sum to approximate the area under the curve. For example, notice the following picture of 19 rectangles of width h = 0.1 ranging from x =1 to x = 2.9.

approx_e_upperThe rectangles all lie below the hyperbola. The width of each one is h = 0.1, and the heights vary from \frac{1}{1.1} to \frac{1}{2.9}. Therefore,

\displaystyle \int_1^{2.9} \frac{dx}{x} > \displaystyle 0.1 \left( \frac{1}{1.1}+ \frac{1}{1.2} + \dots + \frac{1}{2.9} \right)

\displaystyle \int_1^{2.9} \frac{dx}{x} > 1.0326 > 1

In other words, we know that the area between 1 and 2.9 is strictly greater than 1, and therefore a number smaller than 2.9 must be needed to obtain an area equal to 1. So, in a nutshell, we’ve shown that e < 2.9.

Once again, additional rectangles can provide better and better upper bounds on e. However, since rectangles do not approximate the hyperbola as well as trapezoids, we expect the convergence to be much slower. For example, with 100 rectangles of width h, the sum of the areas of the rectangles would be

h \displaystyle \left( \frac{1}{1+h} + \frac{1}{1+2h} + \dots + \frac{1}{1+100h} \right)

It then becomes necessary to plug in numbers for h until we find something that’s decently close to 1 yet greater than 1. Or we can have Mathematica do the work for us:

e_hundredrectanglesSo with 100 rectangles, we can establish that e < 2.7333. With 1000 rectangles, we can establish that e < 2.71977.

Clearly, this is a lot of work for approximating e. With all of the work shown in this post, we have shown that e = 2.71\dots, but we’re not yet sure if the next digit is 8 or 9.

In the next post, we’ll explore the other two ways of thinking about the number e as well as their computational tractability.

Calculators and complex numbers (Part 24)

In this series of posts, I explore properties of complex numbers that explain some surprising answers to exponential and logarithmic problems using a calculator (see video at the bottom of this post). These posts form the basis for a sequence of lectures given to my future secondary teachers.

To begin, we recall that the trigonometric form of a complex number z = a+bi is

z = r(\cos \theta + i \sin \theta) = r e^{i \theta}

where r = |z| = \sqrt{a^2 + b^2} and \tan \theta = b/a, with \theta in the appropriate quadrant. As noted before, this is analogous to converting from rectangular coordinates to polar coordinates.

Theorem. If z = x + i y, where x and y are real numbers, then

e^z = e^x (\cos y + i \sin y)

Definition. Let z = r e^{i \theta} be a complex number so that -\pi < \theta \le \theta. Then we define

\log z = \ln r + i \theta.

Definition. Let z and w be complex numbers so that z \ne 0. Then we define

z^w = e^{w \log z}

Technical point: for the latter two definitions, these are the principal values of the functions. In complex analysis, these are usually considered multiply-defined functions. But I’m not going to worry about this technicality here and will only consider the principal values.

This is the last post in this series, where I state some generalizations of the Laws of Exponents for complex numbers.

In yesterday’s post, we saw that z^{w_1} z^{w_2} = z^{w_1 + w_2} as long as z \ne 0. This prevents something like 0^4 \cdot 0^{-3} = 0^1, since 0^{-3} is undefined.

Theorem. Let z \in \mathbb{C} \setminus \{ 0 \}, w \in \mathbb{C}, and n \in \mathbb{Z}. Then (z^w)^n = z^{wn}.

As we saw in a previous post, the conclusion could be incorrect outside of the above hypothesis, as \displaystyle \left[ (-1)^3 \right]^{1/2} \ne (-1)^{3/2}.

Theorem. Let u \in \mathbb{R} and z \in \mathbb{C}. Then (e^u)^z = e^{uz}.

Theorem. Let x, y > 0 be real numbers and z \in \mathbb{C}. Then x^z y^z = (xy)^z.

Again, the conclusion of the above theorem could be incorrect outside of these hypothesis, as (-2)^{1/2} (-3)^{1/2} \ne \left[ (-2) \cdot (-3) \right]^{1/2}.

green line

For completeness, here’s the movie that I use to engage my students when I begin this sequence of lectures.


Calculators and complex numbers (Part 23)

In this series of posts, I explore properties of complex numbers that explain some surprising answers to exponential and logarithmic problems using a calculator (see video at the bottom of this post). These posts form the basis for a sequence of lectures given to my future secondary teachers.

To begin, we recall that the trigonometric form of a complex number z = a+bi is

z = r(\cos \theta + i \sin \theta) = r e^{i \theta}

where r = |z| = \sqrt{a^2 + b^2} and \tan \theta = b/a, with \theta in the appropriate quadrant. As noted before, this is analogous to converting from rectangular coordinates to polar coordinates.

Theorem. If z = x + i y, where x and y are real numbers, then

e^z = e^x (\cos y + i \sin y)

Definition. Let z = r e^{i \theta} be a complex number so that -\pi < \theta \le \theta. Then we define

\log z = \ln r + i \theta.

Definition. Let z and w be complex numbers so that z \ne 0. Then we define

z^w = e^{w \log z}

Technical point: for the latter two definitions, these are the principal values of the functions. In complex analysis, these are usually considered multiply-defined functions. But I’m not going to worry about this technicality here and will only consider the principal values.

In the remaining posts in this series, I want to explore which properties of exponential functions remain true when complex numbers are used.

To begin, if w is a real rational number, then there is an alternative definition of z^w that matches De Moivre’s Theorem. Happily, the two definitions agree. Suppose that z = r e^{i \theta} with -\pi < \theta \le \pi. Then

z^w = e^{w \log z}

= e^{w [\ln r + i \theta]}

= e^{w \ln r + i w \theta}

= e^{w \ln r} e^{i w \theta}

= r^w (\cos w\theta + i \sin \theta)

Next, one of the Laws of Exponents remains true even for complex numbers:

z^{w_1} z^{w_2} = e^{w_1 \log z} e^{w_2 \log z}

= e^{w_1 \log z + w_2 \log z}

= e^{(w_1 + w_2) \log z}

= z^{w_1 + w_2}.

However, in previous posts, we’ve seen that the rules (x^y)^z = x^(yz) and x^z y^z = (xy)^z may not be true if nonpositive bases, let alone complex bases, are used.

We can also derive the usual rules z^0 = 1 and z^{-w} = \displaystyle \frac{1}{z^w}. First,

z^0 = e^{0 \log z} = e^0 = 1.

Next, we think like an MIT freshman and use the above Law of Exponents to observe that

z^w z^{-w} = z^{w-w} = z^0 = 1.

Dividing, we see that z^{-w} = \displaystyle \frac{1}{z^w}.

green line

For completeness, here’s the movie that I use to engage my students when I begin this sequence of lectures.


Calculators and complex numbers (Part 22)

In this series of posts, I explore properties of complex numbers that explain some surprising answers to exponential and logarithmic problems using a calculator (see video at the bottom of this post). These posts form the basis for a sequence of lectures given to my future secondary teachers.

To begin, we recall that the trigonometric form of a complex number z = a+bi is

z = r(\cos \theta + i \sin \theta) = r e^{i \theta}

where r = |z| = \sqrt{a^2 + b^2} and \tan \theta = b/a, with \theta in the appropriate quadrant. As noted before, this is analogous to converting from rectangular coordinates to polar coordinates.

Theorem. If z = x + i y, where x and y are real numbers, then

e^z = e^x (\cos y + i \sin y)

Definition. Let z = r e^{i \theta} be a complex number so that -\pi < \theta \le \theta. Then we define

\log z = \ln r + i \theta.

At long last, we are now in position to explain the last surprising results from the calculator video below.

Definition. Suppose that z and w are complex numbers so that z \ne 0. Then we define

z^w = e^{w \log z}

Naturally, this definition makes sense if z and w are real numbers.

For example, let’s consider the computation of i^i. For the base of i, we note that

\log i = \log e^{\pi i/ 2} = \displaystyle \frac{\pi i}{2}.

Therefore,

i^i = e^{i \log i} = e^{i \pi i/2} = e^{-\pi/2},

which is (surprisingly) a real number.

As a second example, let’s compute (-8)^i. To begin,

\log(-8) = \log \left( 8 e^{\pi i} \right) = \ln 8 + \pi i.

Therefore,

(-8)^i = e^{i \log(-8)}

= e^{i (\ln 8 + \pi i)}

= e^{-\pi + i \ln 8}

= e^{-\pi} (\cos [\ln 8] + i \sin [ \ln 8 ] )

= e^{-\pi} \cos (\ln 8) + i e^{-\pi} \sin (\ln 8)

In other words, a problem like this is a Precalculus teacher’s dream come true, as it contains e, \ln, \pi, \cos, \sin, and i in a single problem.

green line

For completeness, here’s the movie that I use to engage my students when I begin this sequence of lectures.


Calculators and complex numbers (Part 21)

In this series of posts, I explore properties of complex numbers that explain some surprising answers to exponential and logarithmic problems using a calculator (see video at the bottom of this post). These posts form the basis for a sequence of lectures given to my future secondary teachers.

To begin, we recall that the trigonometric form of a complex number z = a+bi is

z = r(\cos \theta + i \sin \theta) = r e^{i \theta}

where r = |z| = \sqrt{a^2 + b^2} and \tan \theta = b/a, with \theta in the appropriate quadrant. As noted before, this is analogous to converting from rectangular coordinates to polar coordinates.

Over the past few posts, we developed the following theorem for computing e^z in the case that z is a complex number.

Definition. Let z = r e^{i \theta} be a complex number so that -\pi < \theta \le \theta. Then we define

\log z = \ln r + i \theta.

Of course, this looks like what the definition ought to be if one formally applies the Laws of Logarithms to r e^{i \theta}. However, this complex logarithm doesn’t always work the way you’d think it work. For example,

\log \left(e^{2 \pi i} \right) = \log (\cos 2\pi + i \sin 2\pi) = \log 1 = \ln 1 = 0 \ne 2\pi i.

This is analogous to another situation when an inverse function is defined using a restricted domain, like

\sqrt{ (-3)^2 } = \sqrt{9} = 3 \ne -3

or

\sin^{-1} (\sin \pi) = \sin^{-1} 0 = 0 \ne \pi.

The Laws of Logarithms also may not work when nonpositive numbers are used. For example,

\log \left[ (-1) \cdot (-1) \right] = \log 1 = 0,

but

\log(-1) + \log(-1) = \log \left( e^{\pi i} \right) + \log \left( e^{\pi i} \right) = \pi i + \pi i = 2\pi i.

green line

For completeness, here’s the movie that I use to engage my students when I begin this sequence of lectures.


Calculators and complex numbers (Part 20)

In this series of posts, I explore properties of complex numbers that explain some surprising answers to exponential and logarithmic problems using a calculator (see video at the bottom of this post). These posts form the basis for a sequence of lectures given to my future secondary teachers.

To begin, we recall that the trigonometric form of a complex number z = a+bi is

z = r(\cos \theta + i \sin \theta) = r e^{i \theta}

where r = |z| = \sqrt{a^2 + b^2} and \tan \theta = b/a, with \theta in the appropriate quadrant. As noted before, this is analogous to converting from rectangular coordinates to polar coordinates.

Over the past few posts, we developed the following theorem for computing e^z in the case that z is a complex number.

Theorem. If z = x + i y, where x and y are real numbers, then

e^z = e^x (\cos y + i \sin y)

As a consequence, there are infinitely many complex solutions of the equation

e^z = -2 - 2i,

namely, z = \ln 2\sqrt{2} - \displaystyle \frac{3\pi}{4} + 2 \pi n i.

Choosing the solution that has an imaginary part in the interval (-\pi,\pi] leads to the definition of the complex logarithm.
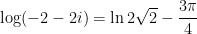
Definition. Let z = r e^{i \theta} be a complex number so that -\pi < \theta \le \theta. Then we define

\log z = \ln r + i \theta.

Of course, this looks like what the definition ought to be if one formally applies the Laws of Logarithms to r e^{i \theta}. So, for example,

\log (-2-2i) = \ln 2\sqrt{2} - \displaystyle \frac{3\pi}{4}

A technicality: this is the principal value of the complex logarithm. In complex analysis, this is technically thought of as a multiply-defined function.

The complex version of the natural logarithm function matches the ordinary definition when applied to real numbers. For example,

\log 6 = \log \left( 6 e^{0i} \right) = \ln 6 + 0 i = \ln 6.

A couple of observations. In high school, the symbol \log is usually dedicated to base 10. However, in higher-level mathematics courses, \log always means natural logarithm. That’s because, for the purposes of abstract mathematics, base-10 logarithms are practically useless. They are helpful for us people since our number system uses base 10; it’s easy for me to estimate \log_{10} 9000, but \ln 9000 requires a little more thought. But nearly all major theorems that involve logarithms specifically employ natural logarithms. Indeed, when I first become a professor, I had to remind myself that my students used \ln for natural logarithms and not \log. Still, I write \log_{10} for base-10 logarithms and not \log as a silent acknowledgment of the use of the symbol in higher-level courses.

This use of the logarithm explains the final results of the calculator in the video below. When \ln(-5) is entered, it assumes that a real answer is expected, and so the calculatore returns an error message. On the other hand, when \ln(-5+0i) is entered, it assumes that the user wants the principal complex logarithm. Since -5+0i = 5 e^{i \pi}, the calculator correctly returns \ln 5 + \pi i as the answer. (Of course, the calculator still uses \ln and not \log to mean natural logarithm.)

green line

For completeness, here’s the movie that I use to engage my students when I begin this sequence of lectures.


Calculators and complex numbers (Part 19)

In this series of posts, I explore properties of complex numbers that explain some surprising answers to exponential and logarithmic problems using a calculator (see video at the bottom of this post). These posts form the basis for a sequence of lectures given to my future secondary teachers.

To begin, we recall that the trigonometric form of a complex number z = a+bi is

z = r(\cos \theta + i \sin \theta) = r e^{i \theta}

where r = |z| = \sqrt{a^2 + b^2} and \tan \theta = b/a, with \theta in the appropriate quadrant. As noted before, this is analogous to converting from rectangular coordinates to polar coordinates.

Over the past few posts, we developed the following theorem for computing e^z in the case that z is a complex number.

Theorem. If z = x + i y, where x and y are real numbers, then

e^z = e^x (\cos y + i \sin y)

Example. Find all complex numbers z so that e^z = 5.

Solution. If z = x + iy, then

e^x (\cos y + i \sin y) = 5 (\cos 0 + i \sin 0)

Matching parts, we see that e^x = 5 and that the angle y must be coterminal with 0 radians. In other words,

x = \ln 5 \qquad and \qquad y = 2\pi n for any integer n.

Therefore, there are infinitely many answers: z = \ln 5 + 2 \pi n i.

Notice that there’s nothing particularly special about the number 5. This could have been any nonzero number, including complex numbers, and there still would have been an infinite number of solutions. (This is completely analogous to solving a trigonometric equation like \sin \theta = 1, which similarly has an infinite number of solutions.) For example, the complex solutions of the equation

e^z = -2 - 2i

are z = \ln 2\sqrt{2} - \displaystyle \frac{3\pi}{4} + 2 \pi n i.

These observations lead to the following theorems, which I’ll state without proof.

Theorem. The range of the function f(z) = e^z is \mathbb{C} \setminus \{ 0 \}.

Theorem. e^z = e^w \Longleftrightarrow z = w + 2\pi n i.

Naturally, these conclusions are different than the normal case when z is assumed to be a real number.

green line

For completeness, here’s the movie that I use to engage my students when I begin this sequence of lectures.